{{previous post in sequence}}


justice-turtle:

You know, as long as I’m thinking about it, let’s run the numbers here, maybe y’all can point out some things I’m overlooking that would make living either more or less expensive than I’m estimating.

Keep reading

>>Depending on what kind of deal I could get on my internet service, it could cost anywhere from $50-$100 a month.<<

…holy shit, I thought paying USD$80 for four people was bad. (I mean, it kind of *is* bad, I’m pretty sure we could save a couple dozen dollars a month if we hadn’t gone and locked ourselves into these guys’ email-address system. We were all young and foolish once.)

>>estimate that everybody’s car drives at least 15k miles a year<<

That’s approximately 40 miles/day on average (including weekends). Does that seem like a reasonable assessment of what a job-having!you is likely to need? It seems kind of high to me; maybe USAA is assuming a pretty long commute?

(Would it be feasible for you to pull your actual figures from when you were a call-center worker by looking at old bank records and such? My own estimates of what my family is likely to spend in the future always start with a baseline of what we actually spent in previous years. I have Google Sheets breaking down our expenses (and incomes) for each of 2016, 2017, and 2018 (updated quarterly) by category.)

>>And iirc my grandfather used to say that you should budget as much for car repairs / maintenance as you do for petrol<<

Mind you, petrol was rather cheaper in your grandfather’s day. I don’t know about you, but our car-repair cost in 2017 equalled 55% of our petrol cost.

>>Meat is fucking expensive, okay? :P<<

It occurs to me that you, too, have a generally cheaper country to the south, not so far away. Can you pull any New-York-style exploitation of cost-of-living differences in Mexico? It’d be pretty bargain-hunty, but I seem to recall you once went to a Mexican dentist to save money, so there’s some precedent. (There are extra language-barrier and border-security issues compared to Canada-to-America cost-of-living tricks, though. Not sure how big those effects are.)

For smaller-scale bargain-hunting, you can try checking around to see if there are any little butchers or anything that sell meat cheaper than your usual grocery chains. The cheapest meat seller in this county (that I know of) is a non-chain grocery store that we overlooked for ages until a friend told us about how cheap their steaks were.

Also, did you get that PM I sent you a while back about how to use Amazon credit at Safeway?

(The offer to sell you Amazon credit at 10% off is still open, if you ever want. Conversion-via-electronics is workable, but it’s a pain and it means the 10% lost goes to some random person on Craigslist. You could pay in USD and I’d deal with the currency-conversion issues myself (and maybe figure out a trick that’ll let me funnel it directly to New York trips and never pay any conversion fees at all; still working on that).)

I also keep a spreadsheet of food prices expressed in cents-per-calorie. Some of them are much cheaper than I expected, notably peanut butter (as cheap as ramen!) and bananas. Plus, even when you’re specifically looking for meat, there’s a lot of price spread between different meats. (Mom occasionally says stuff about not really being able to afford a diabetic-friendly diet, and I always tell her there’s still *relative* cheapness to be found even within medical restrictions. If she thinks she ought to spend less on food, she can replace some of her canned tuna with (non-canned) chicken (which costs half as much).) I can’t be too specific without more knowledge of your own local food prices than I have, but some things to keep in mind.

>>Do any of you know what one normally spends on this sort of thing?<<

I don’t. My expense-tracking spreadsheets work at the granularity of a transaction, which means most sundries get lumped in with groceries under “things bought at grocery stores”.

>>I am reluctant to switch too much up on that, as due to some interesting bits of luck, I am currently month-to-month rather than on a contract.<<

Is that difficult to come by in America? (And here they told me Canada had some of the worst cell plans out there, far worse than America.)

Recently I systematically went through every cell brand with coverage in this area and compared their plans (all of them had no-contract options, though they weren’t always front-and-centre), which is why I was able to find Dad a $40/month plan big enough to cover his work needs. The main thing I learned was to *never ever* buy from a flagship brand: buy from a little reseller or offshoot brand instead. (Holy shit, do the Big Three ever overcharge on their flagship-brand plans.) But, again, the Canadian cell-plan situation is famously weird, so I don’t really know what Arizona is like with that.

How much mobile data do you have? How much do you need? How much data can you offload onto non-mobile-data versions of the same thing? (…she says, as someone who carries an offline copy of Wikipedia with her at all times and has memorised the location and size of every public Wi-Fi hotspot within walking distance†.) Can you arrange to downgrade? (I know you need some mobile data for mental-health reasons, but like with Mom eating chicken instead of fish, sometimes there’s still room to do less-expensive versions of a necessary expensive thing.)

>>Laundry. Roughly $5 a week at the laundromat for one large load of laundry. This covers the amount of laundry I generate, which I know because my aunt hauls me to the laundromat every week. Still, it adds up; $260 a year for laundry, not counting detergent (which goes under Sundries). *sigh*<<

Does that mean it’s safe to assume the Hypothetical Apartment won’t come with a washing machine and dryer? I’ve always had a washing machine and dryer in my house, so I have no idea how to optimise laundromat usage. (My laundry optimisation looks like “run the machine during off-peak hours to reduce its electricity cost”.)

>>Clothes. Once again I haven’t the faintest notion how much these actually cost.<<

I haven’t bought much in the way of new clothes since I started keeping track of expenses (I haven’t finished wearing out all my clothes from before), so neither do I. When I do buy clothes these days, I generally buy from thrift stores, but I suspect you’d have a lot of trouble trying to find anything there in your size.

(Mom is somewhere around your size, and she managed to get a 50%-off birthday coupon from a Canadian plus-size clothing chain after signing up for their mailing list.)

You could really do with some housemates who don’t suck so you could get some bulk discounts happening, but if that were actionable advice you’d probably have done it already.

*hugs*

—

†And keeps being surprised and kind of horrified by how little attention her offline friends and acquaintances pay to minimising their data usage. (Do you know how many people I’ve met at Wi-Fi-blanketed Pokemon gyms who *didn’t know* they were in a Wi-Fi zone? (No wonder they’d been so surprised when I told them I was able to play Pokemon Go 1 – 2 hours/day on a 100 MB/month plan.) Do you know I once had a friend burn through her entire month’s allotment in four days, and she neither knew nor cared why?)


Tags:

#reply via reblog #adventures in human capitalism #our home and cherished land #home of the brave #disordered eating?

justice-turtle:

justice-turtle:

Yeah, I’ve just now run the numbers and in order to support myself on minimum wage without any roommates or government assistance, I would need to work full time and also quit karate. (At $99 a month, karate is quite a lot of money.)

Part of that is that y’all are splitting both rent and working hours among a whole family. Part of it may or may not be your part of Canada having a different minimum wage compared to cost of living, I haven’t looked up that part. (Arizona’s minimum wage is $10.50 USD an hour, which is A Lot compared to the federal minimum wage of $7.25 USD, but for comparison a one-bedroom apartment is about $500 a month plus utilities.)

Part of it is definitely that feeling Poor – bargain-hunting, cooking scratch meals, fiddling with threadbare or only-semi-working possessions, inability to afford a few shinies – stresses me out more than the extra spoon expenditure warrants, and (it’s my impression) way more than it does you. That’s a psychological flip that happened during / due to the Remodel of Doom; there’ll probably be a separate post on that at some point. Tumblr tends to eat mobile photo posts with a lot of text, so I’m gonna go ahead and post this before it gets too long.

Oh – yeah, Uber/Lyft is off the table for a few reasons. My car is extremely elderly (1996 model year), I don’t live in a large enough metropolitan area that anybody local actually uses those services, and I really strongly dislike having anyone else in my car – it’s the only space where I actually feel safe and in control, and having other people in it shorts that out. :P So, yeah.

Yeah, I can think of some reasons why I’m in a much better position to live cheaply than most people:

  • Four adults, zero children. Both halves of that are pretty huge, I expect.
  • Because we used to be a lot richer than we are now, we were able to end up in a situation where we rent from a mortgage company† instead of a landlord, which costs about half as much as the going rate for a local house of this size (~$800/month instead of ~$1,600).
  • While there *were* children in the household when we moved in, they were homeschooled and expected to (and did) remain so, so school district was not really a factor in the housing decision. (Apparently competition over good school districts drives up the price of housing a lot? So I’m told, anyway.) (I honestly don’t even know what our school district’s reputation is.)
  • I walk to work and my parents carpool with each other, so there are only two cars’ worth of commute expenses for four people.
  • No student loans. We paid for Brother’s culinary school out of pocket, and we’re currently paying for my university out of pocket (a mix of my wages and the mutual fund my relatives gave me as a baby for my education). I don’t really think of student loans as an option: if I ever reach a point where I can’t scrape together $820 for a university course††, I’ll stop going until and unless I can afford it again.
  • 2 – 4 times a year, we drive to New York, exploit their lower cost of living (and the fact that we still have enough savings between us to do things like “spend $800 in one day to avoid spending $1,400 over four months”) to stock up on cheap groceries, drive back, and store the cold items in our three freezers.
  • The medication assistance program caps our prescription expenses at 4% of our income, IIRC. Not going to be nearly as useful now that we’re making more, though. (Note: currently, only my parents have chronic prescriptions.)
  • (However, we don’t have food stamps, because those aren’t really a thing here.)
  • The foods I genuinely enjoy and want to eat frequently mostly happen to be cheap, plus I have a low metabolism (and an appetite to match). (This might be cancelled out by Mom being diabetic, so having to eat a fairly expensive diet for health reasons.)
  • I continue to not have a cell plan, and everyone else is on light-use $100/year plans. (Dad’s going to have to upgrade soon to a $40/month plan, though, because he’s now using his phone a lot for work.)
  • Apparently we use very little water? I wouldn’t have thought so, but we got a pamphlet from the county government a while back talking about how to use less water, and when we compared their figures to ours we found that we use *half* as much water as the average *three*-person household. I’m not sure what’s going on there.
  • Plus, you know, free healthcare in most aspects. The usual counter is “oh, you’re still paying health insurance, it’s just integrated into your taxes”, but we paid, like, negative three thousand dollars in taxes last year, so.
  • Probably other stuff I don’t even realise.

—

The minimum wage here is currently CAD$14/hour (theoretically USD$10.75, if you completely ignore cost of living and just do a straight exchange-rate), but I don’t know if that actually means much in practice, or if the prices just change to compensate, or what. (Mind you, the prices in *New York* grocery stores probably wouldn’t change to compensate for a high Ontario wage, would they…)

—

(While some of these are dwindling-savings!poor vs paycheck-to-paycheck!poor, there are still things that would save money in the long run that we don’t have enough savings to pull off. Personally, I dream of one day being able to afford a plug-in hybrid car. They cost like $20k (*maybe* $13k if you can find a used one), but *damn* are they cheap to run (especially in an area with cheap electricity and expensive gasoline†††, as we are).)

—

>>feeling Poor […] stresses me out more than the extra spoon expenditure warrants, and (it’s my impression) way more than it does you.<<

Yeah, seems like it.

Relatedly: I hear sometimes about this placebo-effect-type thing where people enjoy food more if it’s (or they believe it to be) expensive? I think I have the opposite of that: I enjoy food more if it’s cheap. Peanut butter is already pretty tasty in isolation, but its tastiness is enhanced by the comfortable knowledge that this was a *fantastic* use of fifteen cents. Whereas I have trouble fully enjoying restaurant food, because there’s a part of me wondering if it’s really possible for any food to be worth this much when there are all these good cheap foods out there.

—

The other-people-in-your-car thing wouldn’t prevent freelance food-delivery, which is why I was thinking Uber Eats. The elderly-car thing probably would, though, as would the small-population thing. (There are definitely advantages to living in a county of 600k.)

—

I’ll go look at your number-crunching and see if I can find anything.

—

†Interest-only payments on a *very* large amount of house debt. I think it’s pretty fair to characterise this as “renting from a mortgage company” for most purposes, though it also comes with better tenants’ rights.

††That might be a factor in itself. I’ve definitely known people who were paying a lot more than that per course.

†††Although not quite as expensive as I thought; I think I wasn’t fully factoring in the exchange rate, and the thing where a gallon is a bit *less* than four litres (so multiplying a per-litre price by four gives you an overestimate of the per-gallon price). WolframAlpha says the figure at the local gas station translates to USD$3.75/gallon.


Tags:

#reply via reblog #adventures in human capitalism #long post #disordered eating?


{{next post in sequence}}

{{previous post in sequence}}


brin-bellway:

riker-wears-a-skant:

GUYS GUYS GUYS

I JUST REALIZED A THING

WORF AND JADZIA GET MARRIED IN “YOU ARE CORDIALLY INVITED” BUT EARLIER IN THE EPISODE SISKO CHEWS DAX OUT FOR BEING CHILDISH WHEN SHE’S 356 YEARS OLD

“YOU ARE CORDIALLY INVITED” TAKES PLACE IN EARLY 2374

THE DAX SYMBIONT IS THEREFORE BORN IN 2018

WE’RE GONNA HAVE TO THROW A PARTY WORTHY OF CURZON IN ABOUT FIVE YEARS

IT’S GONNA BE AWESOME

January 3rd? (It would be the anniversary of Dax’s first appearance, which seems pretty good as arbitrary dates go.)

#Memory Alpha was way ahead of you   #but I didn’t know where they got 2018 and hadn’t thought through the full implications

Was digging through some ancient Tumblr posts and stumbled across this.

I completely missed January 3rd (maybe back in the day I should have tried queueing something for what was then several years in the future?), but hey, happy birth year, Dax!


Tags:

#Star Trek #DS9 #birthday #oh look an update

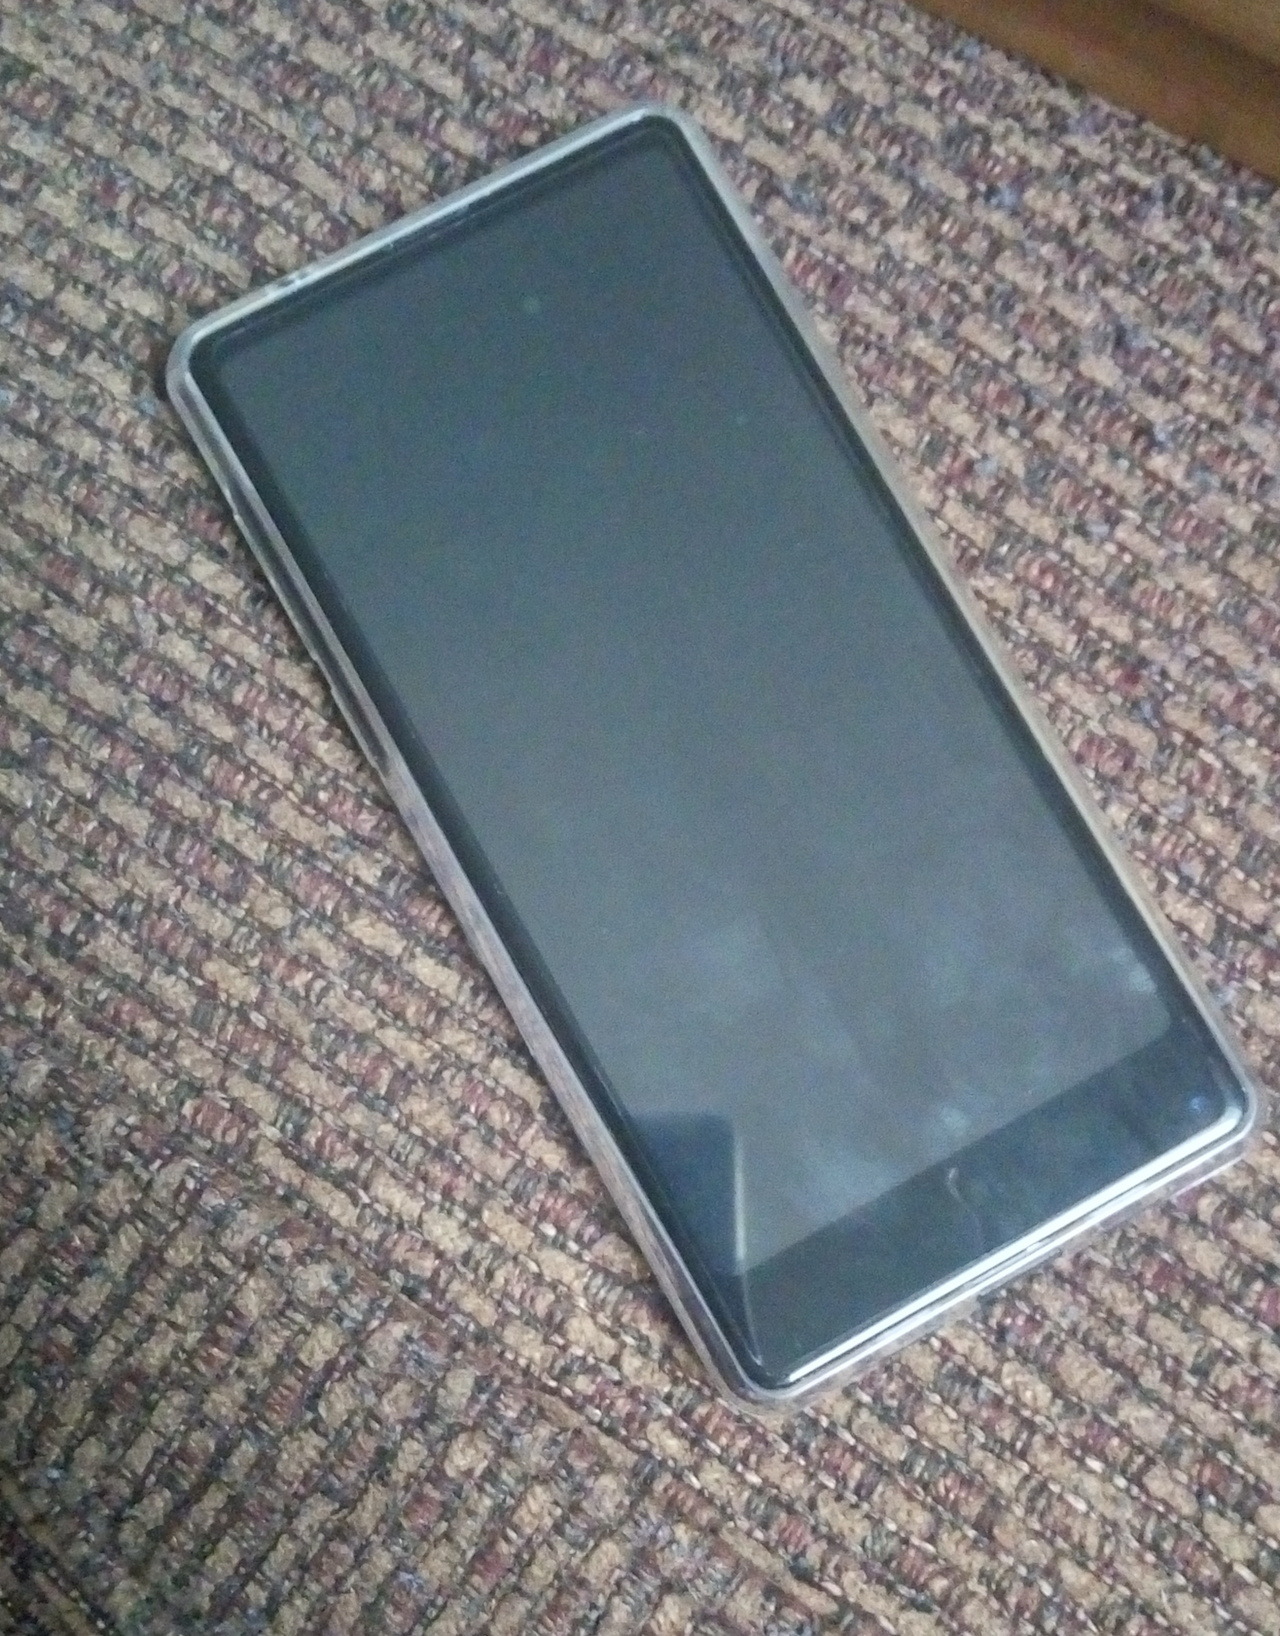
Pictured (an incomplete list): over a decade of diary entries, several years of dream journal, a few years of chat logs, copies of the comments I’ve left on blog posts (sadly incomplete, but far better than nothing), email archives for all three and a half of the email addresses I care about, tens of millions of words of fiction, a few hundred songs, a complete set of the Red Panda Adventures (including books and video comics), Wi-Fi maps for several cities I am relatively likely to find myself in, buggier and less-thorough Wi-Fi maps for the entirety of Canada and the United States, regular maps for every province/state I’m likely to visit in the normal course of events (Ontario, New York, Massachusetts), complete copies (including images) of several Tumblrs (including but not limited to mine), and the full text (but not images) of Wiktionary and Wikipedia.


Tags:

#I take great comfort in carrying my Useful Thing collection around with me all the time #and I have applied this same mindset to information #(the text portion of this post has been lying around in my drafts for so long that I’ve actually gotten a new smartphone since then) #((picture is of the new phone; taken using the old phone’s camera)) #(it’s still true it’s just that the portable version of my personal archive has a different physical embodiment now) #Brin owns *two* 2010’s computers now #(currently three; I plan to sell the old one soon to recoup most of what I spent on the new one) #proud citizen of The Future #oh look an original post #in a couple of days I’ll do the next backup and this post itself will become part of my archive #(the following category tag was added retroactively:) #101 Uses for Infrastructureless Computers

{{previous post in sequence}}


3dspacejesus Icon

@3dspacejesus

​ replied to your post

“cryptovexillologist:

By the way: my main social media presence these…”

I think dragon.style has a 5000-character limit

*looks at dragon.style*

7777-character limit, which seems pretty workable even though I don’t really understand why there’s a character limit at all (though I notice a lot of the articles about Mastodon were written by people accustomed to Twitter who think 500 characters is a lot). Downsides: not currently accepting new accounts, some of the admin’s attempts to signal safety are of a kind that–from past experience–I actually parse as hostile instead (in a “will probably turn you in to the Thought Police” kind of way).

Still, proof of concept, and it’s possible Anthracite isn’t actually as scary as the people whose signals she’s using. (She does at least appear to have zero obscenity laws as long as you use content warnings and cuts, which is very important to me in a venue because…well, here is a quote from a PM I sent a while back regarding why I wasn’t going to move to Imzy:

“IME, obscenity laws are enforced more strictly the less sexually mainstream you are, and as someone who is about as non-mainstream as it gets, the strictures on me get very tight very fast once they start existing at all. (Good thing I’m not into bondage, or it’d probably cause a paradox. :P) It tends to work out that if straight people can’t have sex, then gay people can’t kiss and fetishists can’t talk, and dammit I *like* talking.

Basically, I don’t trust any site with any obscenity rules at all to let me post the thing I just posted {{note: the thing in question was this}}. (And woe unto anyone who tries to distribute [things that are in a grey area between porn and sex toys] like half the people in my kinky Tumblr‑sphere do.)”)


Tags:

#3dspacejesus #replies #our roads may be golden or broken or lost #sexuality and lack thereof #(the following category tag was added retroactively:) #Fediverse

{{previous post in sequence}}


brin-bellway:

Relatedly:

Keep reading

Update: as of today, all three of these problems are gone.

* Last summer, a guy I bumped into at a Pokemon gym inducted me into the local raid-coordination chat. I’m still pretty bad at actually *catching* them, but I’ve made it to the catch screen a fair number of times (and got some TMs!), and I did get an Arcanine.

* Today I checked the Discovery Channel website just in case things had improved, and they *had*: it looks like they’ve gone back to ad-supported streaming, and no longer require a TV subscription. I watched Daily Planet today, for the first time in about a year!

* Learned last autumn that I could indirectly sell Amazon credit (taking roughly as much loss as I’d expected to take selling directly) by buying electronics on Amazon and then immediately turning around and selling them on eBay/Craigslist/suchlike. Still not as good as extracting the full value from the credit, but it’s something. (and they continue to expand their gift-card section! still have hope for eventual Wegmans! *crosses fingers*)


Tags:

#oh look an update #in which Brin learns to speak Pokemon #adventures in human capitalism


{{next post in sequence}}

cryptovexillologist:

By the way: my main social media presence these days is at Mastodon.social/@cryptovexillologist

And I just added a new profile, chitter.xyz/@Zipporah_Cryptovex, that’s mostly me rambling about gender introspection

Mastodon is a baller social network, and I hope this sways at least one of you to come join me there

Do they still have that 500-character limit?

I tried looking into Mastodon a while back, saw the 500-character limit, and noped right back out. Recently I *think* I heard something on the Tumblr grapevine about the character limit only applying on some instances, but I’m not sure I heard that right, nor (if true) how to go about finding an instance that isn’t so restrictive.


Tags:

#Mastodon #reply via reblog #(the following category tag was added retroactively:) #Fediverse


{{next post in sequence}}

How to credit card

serinemolecule:

spiralingintocontrol:

serinemolecule:

Using a credit card is like paying with cash, except you also get free money and other benefits.

“But Serine, there’s no such thing as a free lunch! [1] Where does the money come from?”

I’m glad you asked. When you buy something with cash, the seller gets 100% of what you pay. When you use a credit card, the seller gets around 97% of what you pay, and the companies involved in handling the payment get around 3%. [2] This includes the credit card company, which is very willing to give you money and other benefits if you choose them to get the rest of that 3%. [3]

Sellers are willing to give up 3% because handling credit cards is so much easier than cash. You don’t have to count change, and you have a computer record of who paid how much, so it’s easy to figure out who’s lying when the customer said they paid. Not to mention it eliminates the problem of cashiers stealing money by pocketing customers’ money [4]. Also not to mention the store wants the customer to be happy (happy customers spend more) (customers hate having to pay a fee to use a credit card).

Anyway, in the general case, credit cards are basically always a good thing, and you should basically always use them. [5]

When not to credit card

If you are irresponsible with money, and are afraid you will spend more money than you have, you should not use a credit card. Never carry a balance on a credit card (pay off less than the total amount you owe), it piles up and ruins your life. You should spend money on getting things you want, not on paying off interest.

What benefits you get from using credit cards

Most credit cards will give you 1%-2% cash back (for each dollar you spend, you get a certain percentage back in free money).

Basically all credit cards give you the ability to chargeback. This means that if some business steals your money (charges you more than you owe, etc) and you can prove it, you can call the credit card company and tell them to take your money back. Note that this is a last resort (only to be used after you contact the business and they don’t give you your money back), and will generally result in the business completely cutting off contact with you (for instance, if you chargeback Steam, you’ll lose access to all your Steam games etc).

Credit cards also act as a short-term loan. If you ever need a payday loan, a credit card will give you significantly less interest than an actual payday loan. You never want a credit card as a long-term loan (the rates are horrible), but they actually give you close to the best possible rate for a short-term loan. Just remember that debt is evil and never to fall into it.

Other benefits vary wildly and are specific to the card, but common benefits include various forms of insurance (car insurance on any rental car you rent with the credit card, warranty on anything you buy, etc).

Which card to get

It’s actually really easy to choose a credit card. If you’re in the US, here is Serine’s One-Step Guide:

Do you spend more than $2500 per year in travel (hotels, flights, Ubers, etc) and restaurants?

– No -> Get the Citi DoubleCash

– Yes -> Get the Chase Sapphire Reserve

In some extremely obscure situations, you might want other cards, but I’ll cover those after I cover these two cards.

The Citi DoubleCash

The Citi DoubleCash has no yearly fee, and gives you 2% cash back, effectively. This makes it better in every way than most other cards.

Some cards give 1% cash back and a rotating 5% category. They will give you a headache trying to optimize them and you will still get less money back compared to the Citi DoubleCash, in the end.

Some cards give you points that you can spend using a complicated procedure, which will be worth approximately 2% if you can spend them perfectly. Just use the Citi DoubleCash, and skip the complicated procedure.

The Chase Sapphire Reserve

The Chase Sapphire Reserve has a $450 yearly fee, and gives a huge number of benefits that are totally worth it if you spend a decent amount of money. Also it looks really cool because it’s metal and black. [6]

It comes with $300 of travel credit per year, which you can blow through in, like, a single flight, or like a few days of hotel, or like a normal amount of Ubering (anyone who’s even considering this card should have no problem spending that much). So the yearly fee is effectively $150.

It gives you 3 points per dollar on travel and restaurants, and 1 point per dollar on anything else. “Points” can and should be converted to frequent flyer miles, at which point they’re worth 2-4 cents each if you put them towards international flights, especially international first-class flights.

It also comes with a pile of side-benefits, like free Priority Pass membership (gives access to a bunch of airport lounges), and free TSA Global Entry (lets you basically skip airport security and customs).

Assuming you spend enough and you’re willing to spend the effort optimizing flyer miles, it basically pays for itself and the other benefits are free.

Honorable Mention: The AmEx Platinum

I know I didn’t mention the AmEx Platinum at all, but if you have lots of money and want the best benefits on a card (or you take a lot of flights), the AmEx Platinum is probably the card for you.

The AmEx Platinum costs $550 per year, and is a luxury card pretty similar to the Chase Sapphire Reserve. Its biggest advantage is that it has much better airport lounge coverage in the US.

Priority Pass (which comes with both the Chase and the AmEx) gives you lounge access for most international flights, but the AmEx Platinum also gives you lounge access for US domestic flights.

It gives 5 points/dollar for airfare and AmEx Travel hotel purchases, and 1 point/dollar for other purchases, and its points can also be turned into flyer miles.

Other advantages include Gold membership status at Hilton, Marriott, Starwood, and Ritz-Carlton hotels. Mostly this means guaranteed late-checkout at all of those except Hilton, and, like, free bottled water sometimes.

Instead of the $300 travel credit, though, the Platinum has a $200 airline fee credit (abusable to buy gift cards) and a $200 Uber credit (spread out across 12 months, so hard to maximize unless you use Uber all the time). It’s harder to max these out, but if you do, it’s also effectively $150/year.

Overall, the main reason you’d actually want the Platinum over the Sapphire Reserve is if you fly a lot in the US and really want the additional airport lounges.

Extremely obscure situations

So the most common one is: If you have a ton of free time and spend a decent amount of money, you might be interested in churning. I don’t really want anything to do with churning so you’re going to have to learn how to do it from someone else (google it, I guess).

If you travel internationally, be aware that the Citi DoubleCash has a foreign transaction fee. It’s still worth it (2%, which is still less than the fee you’ll be charged by most money exchangers – Wells Fargo takes like 5%), but it’s also not very hard to just get a credit card that doesn’t have that fee. The Amazon Prime card and the Costco credit card are good options (these two are pretty good cards to have in general, honestly; they have no yearly fee and a few specific uses, just don’t use them as your main card because they don’t have the 2% base rate the DoubleCash has).

That’s it

I haven’t actually taught you how to spend money wisely (maybe that’ll be a different post), but at least you can get more value out of the money you do spend now.


[1] In a way, there’s no such thing as a free lunch, but in a way, there totally is. Like, think about breathing (but not too hard – I don’t want you to start manually breathing – …I’m sorry). There are some minor trade-offs (you have to use energy) and situations where you shouldn’t (do not breathe while underwater unless you have special equipment) but overall, it’s basically always correct to choose “breathing” over “not breathing”.

[2] The 3%ish is split kind of complicatedly, in terms of who gets what. The credit card company definitely gets most of it, though.

[3] And also to get your late payment fees and interest and stuff, but honestly, credit card rewards come out of the processing fee.

[4] It’s easiest for cashiers to steal money if you’re selling something hard to track, like french fries. A cashier can give a customer some french fries, pocket the customer’s money, and the store owner would never know. This is why a lot of fast food places say “free food if we don’t give you a receipt”. The receipt makes sure the cashier gives the store owner the money.

[5] Some stores don’t accept credit cards. These are very very rare in the US, and mostly restricted to, like, certain vending machines, and tiny stores that hate the 3% transaction fee. Also, a lot of service workers prefer you to tip in cash, because that makes tax evasion easier (it’s up to you whether you consider this a good thing or a bad thing).

[6] You can tell people it’s “the black card” and they’ll totally believe you (it’s not) (also remember to tell them you were joking about it being “the black card”; you don’t want to be that asshole who lies about dumb stuff like this).

Interesting! On a politics note, I will say that at least some of the “free money” you get from credit cards comes from secretly skimming off of everyone else: Credit card companies generally prohibit stores from charging more to credit card users, which means the fees have to be spread out over everyone by increasing prices slightly on average.

Maybe I should get the Chase Sapphire Reserve… I travel a lot…

I didn’t go over that part, because opinions are kind of mixed on whether or not handling cash or handling credit cards is actually more expensive, after all the fees and costs and varying levels of theft.

Like, fraud costs, miscounting money, etc are a lot lower with credit cards, so who is really skimming off whom?

(Empirically, though, mom-and-pop small businesses seem to prefer cash, so feel free to use cash at those places, if it makes you feel better.)


Tags:

#interesting #home of the brave #adventures in human capitalism #all I have right now is a little 0.5% card from my bank because it was all I could get with no credit history #(fortunately I’ve been with that bank for 10+ years and never caused them any problems) #(so they trusted me enough to help me bootstrap into having a credit history) #but yeah I definitely do take cashback into account for financial analyses #(”hey Dad can we put my university course on your card? we’ll save an extra four dollars versus putting it on mine”) #anyway I found this post buried in my open tabs and realised I forgot to reblog it #so here it is